
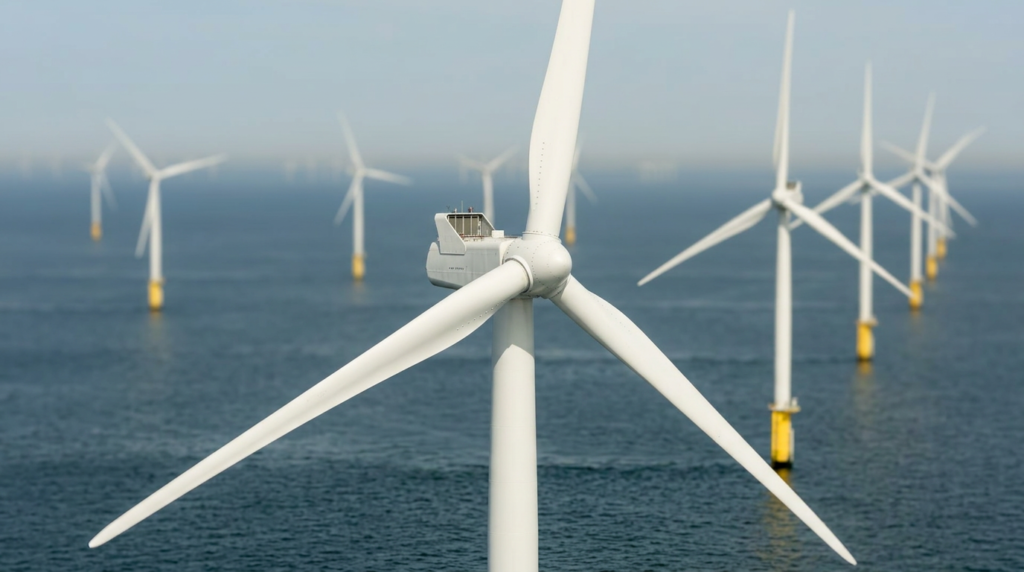
Six offshore wind trends are shaping 2027: rapid capacity growth, the rise of floating wind, larger turbines, a widening skills shortage, digital transformation of operations, and the emergence of new regional markets. Together, these shifts are redefining how projects are planned, staffed, and executed around the world. If you work in offshore wind — or want to — understanding these trends helps you make smarter decisions about where the opportunities are and what they demand.
How fast is the offshore wind industry expected to grow by 2027?
The offshore wind industry is on track to add significant new capacity by 2027, with global installed capacity projected to more than double compared to where it stood just a few years ago. Growth is being driven by government commitments in Europe, the United States, and Asia, combined with falling technology costs that make offshore wind increasingly competitive with conventional energy sources.
Europe remains the largest market by installed capacity, but the pace of development in the United States and parts of Asia is accelerating rapidly. The UK, Germany, the Netherlands, and Denmark continue to commission major projects, while the US East Coast pipeline is translating policy ambition into actual construction activity. This volume of work creates enormous demand across the entire supply chain — from engineering and installation to operations and maintenance.
For businesses operating in this space, the growth trajectory means more projects running simultaneously, tighter timelines, and greater competition for qualified personnel. Workforce planning is no longer something you can leave until a project is awarded. The companies that prepare early are the ones that keep their schedules on track.
What role does floating offshore wind play in 2027 plans?
Floating offshore wind is moving from demonstration projects to early commercial deployment by 2027. Unlike fixed-bottom turbines, floating foundations can be installed in deeper waters — typically beyond 60 metres — which opens up vast new areas of ocean that were previously inaccessible. This is particularly relevant for countries like Japan, South Korea, Norway, and parts of the United States where the seabed drops steeply close to shore.
Several commercial-scale floating wind projects are in advanced development stages, and the supply chains supporting them are beginning to take shape. The technology still carries a higher cost per megawatt than fixed-bottom wind, but costs are coming down as more projects are built and operational experience accumulates.
From a workforce perspective, floating wind introduces new technical requirements. Installation methods differ from conventional offshore wind, and operations and maintenance on floating platforms require specific skills and safety training. Professionals with backgrounds in oil and gas — particularly those familiar with mooring systems, dynamic cables, and floating structures — are finding their expertise highly transferable to this sector. You can explore open offshore wind roles that reflect exactly this crossover demand.
How are larger turbines changing offshore wind project economics?
Larger turbines are making offshore wind projects more cost-effective by generating more electricity from fewer units, which reduces the number of foundations, cables, and installation vessel trips required. Turbines in the 15 to 20 megawatt range are now entering commercial deployment, and manufacturers are already developing designs beyond that threshold.
The economic logic is straightforward: fewer turbines per project means lower installation costs per megawatt of capacity, even though each individual turbine is more expensive and complex to handle. This shifts the economics of a project significantly in favour of larger machines when the right vessels and port infrastructure are available.
However, larger turbines also raise the bar for the workforce. Technicians need updated training to work safely at greater heights and with heavier components. Installation engineers must adapt their planning to the logistics of handling blades that now exceed 100 metres in length. The skills gap between what the industry needs and what the available workforce currently has is widening as a direct result of this technology shift.
What is driving the offshore wind skills shortage in 2027?
The offshore wind skills shortage in 2027 is driven by three converging pressures: rapid industry expansion, the retirement of experienced workers from adjacent sectors, and the technical demands of newer technology. The industry is growing faster than training pipelines can produce qualified professionals, creating a structural imbalance between supply and demand for skilled personnel.
The shortage is particularly acute in roles that require both offshore experience and renewable energy knowledge — such as commissioning engineers, installation supervisors, and dynamic positioning officers for specialist vessels. Many of these professionals have historically come from oil and gas or maritime backgrounds, and while that crossover remains valuable, the transition is not always straightforward without targeted upskilling.
Geography adds another layer of complexity. Projects are being developed in regions where local talent pools are limited, which means international recruitment and cross-border workforce deployment are not optional extras — they are operational necessities. Getting the right people to the right location, with the right contracts and compliant payroll arrangements, is one of the defining challenges for project managers in this industry right now. Exploring the full range of sectors we serve gives a clear picture of how interconnected the talent markets across maritime, renewables, and oil and gas really are.
How are digital technologies transforming offshore wind operations?
Digital technologies are transforming offshore wind operations by enabling predictive maintenance, remote monitoring, and data-driven decision-making that reduce downtime and lower operational costs. Sensors embedded in turbines generate continuous data streams that, when analysed correctly, allow operators to identify potential failures before they happen rather than responding after the fact.
Drones are now routinely used for blade inspections, reducing the need for technicians to work at height and cutting inspection time significantly. Remote operations centres allow teams onshore to monitor entire wind farms in real time, which changes the staffing model for offshore assets — fewer people need to be physically present on a platform for routine monitoring tasks.
Digital twins — virtual models of physical assets — are becoming standard tools for planning maintenance schedules and simulating the impact of operational changes. This shift towards data-intensive operations means the offshore wind workforce of 2027 increasingly needs digital literacy alongside traditional technical skills. Engineers who can interpret operational data and work with software platforms are in high demand across the sector.
Which regions are emerging as new offshore wind markets in 2027?
The most active emerging offshore wind markets in 2027 are the United States, Taiwan, South Korea, India, and parts of the Middle East and North Africa. Each of these regions is at a different stage of development, but all have made policy commitments that are translating into real project activity and supply chain investment.
The United States is the largest new market by potential, with a substantial pipeline of projects along the East Coast and growing activity on the West Coast for floating wind. Taiwan has established itself as Asia’s most mature offshore wind market outside of China, with a strong local content framework that is shaping how international companies participate. South Korea is scaling up quickly, and India’s ambitions are backed by significant government targets for offshore capacity by the end of the decade.
In the Middle East, Saudi Arabia and the UAE are exploring offshore renewables as part of broader energy diversification strategies. For staffing and workforce planning, these emerging markets create both opportunity and complexity. Local regulations, visa requirements, and labour laws vary significantly, and international project teams need partners who understand the rules on the ground. We have offices and representatives in Dubai, Saudi Arabia, Mexico, and the United States, which means we know the local market conditions and compliance requirements in several of these fast-growing regions — not just in theory, but in daily practice.
How iPS Powerful People helps with offshore wind staffing
We have been placing professionals in demanding technical industries for more than 35 years, and offshore wind is one of our most active sectors. Whether you need a single specialist for a short-term assignment or a complete crew for a multi-year installation project, we handle the full picture — recruitment, crewing, and cross-border payroll — so you can focus on delivering the project.
- Recruitment and crewing: We source qualified offshore wind professionals from our database of over 100,000 candidates, including engineers, installation supervisors, technicians, and vessel crew.
- Full project staffing: We can take on the complete workforce planning and deployment for an offshore wind project, from survey phase through to commissioning and operations.
- Cross-border payroll and compliance: We place candidates on our own payroll, handle A1 certificates within the EU, and ensure full compliance with local labour law — so you carry no administrative or legal risk.
- Global reach, local knowledge: With offices in the Netherlands, the Baltic States, Croatia, Dubai, Saudi Arabia, Mexico, and the United States, we understand the regulatory environment in the markets where offshore wind is growing fastest.
- Safety and qualifications screening: Every candidate we place meets the QHSE requirements and international safety standards relevant to their role. This is a non-negotiable part of every placement we make.
Ready to talk about your offshore wind workforce needs? Learn more about who we are and what drives us, or get in touch with our team directly to discuss your project.