
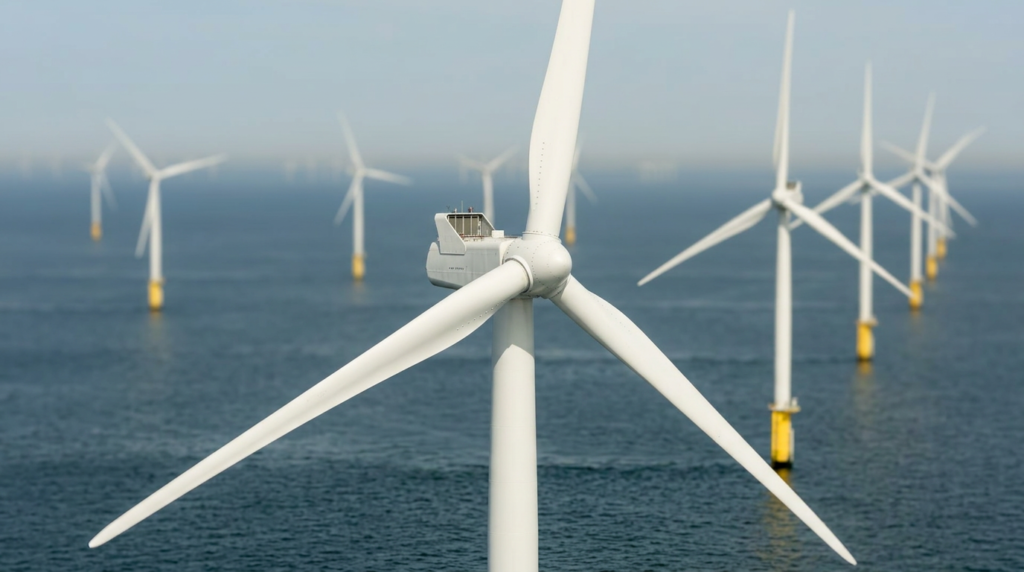
Offshore projects attract investment when they combine strong energy demand, clear regulatory support, and a realistic path to return on capital. The most funded offshore projects in 2026 are concentrated in wind energy, oil and gas production, and large-scale civil infrastructure. This article walks through the key questions investors and project developers are asking right now.
What makes an offshore project financially viable to investors?
An offshore project becomes financially viable when its projected revenues reliably exceed its total lifecycle costs, including development, construction, operations, and decommissioning. Investors look for a combination of stable cash flows, manageable risk exposure, and a clear regulatory framework before committing capital to any offshore venture.
Several factors drive viability in practice. Long-term offtake agreements, such as power purchase agreements in renewables or production-sharing contracts in oil and gas, give investors confidence that revenues will materialize. Proximity to infrastructure, whether that is port access, grid connections, or pipeline networks, directly reduces capital expenditure. Water depth, weather conditions, and seabed geology all affect construction costs and therefore the overall business case.
Project size also matters. Larger offshore projects benefit from economies of scale that improve cost per unit of output. However, scale increases execution risk, which is why investors pay close attention to the track record of the project developer and the quality of the workforce being deployed.
Which types of offshore energy projects receive the most funding?
Offshore wind projects receive the largest share of new investment in offshore energy, followed by oil and gas production developments and, increasingly, floating solar and hydrogen infrastructure. Offshore wind has become the dominant recipient of capital because of falling technology costs and strong government support across Europe, Asia, and North America.
Within oil and gas, deepwater and ultra-deepwater developments continue to attract significant funding where proven reserves justify the cost. Brownfield expansions at existing platforms also draw investment because the infrastructure is already in place, reducing upfront spend.
Emerging categories gaining traction include:
- Floating offshore wind, which opens up deeper water sites previously inaccessible to fixed-bottom turbines
- Offshore hydrogen production, linked to wind farms and positioned as a long-term energy carrier
- Carbon capture and storage (CCS) projects using depleted offshore reservoirs
- Subsea cable infrastructure connecting offshore generation to onshore grids
Investors active in the maritime and energy industries are tracking all of these categories closely as the energy transition reshapes capital flows.
How do government policies influence offshore project investment?
Government policy is one of the strongest drivers of offshore project investment because it directly affects revenue certainty, permitting timelines, and risk allocation. Subsidies, tax incentives, and contract-for-difference mechanisms can make a marginal project commercially attractive. Conversely, regulatory uncertainty or sudden policy reversals can stall investment entirely.
In Europe, national offshore wind targets backed by auction frameworks have created predictable pipelines that attract institutional capital. In the Gulf of Mexico, federal leasing programs determine where oil and gas development can legally occur. In Southeast Asia, government-to-government agreements often set the terms for offshore energy development.
Permitting speed is another policy variable that investors weigh heavily. A project that takes three years to permit carries more financing risk than one with a streamlined approval process. Countries that have simplified offshore permitting in recent years have seen a measurable increase in project announcements.
What is the difference between greenfield and brownfield offshore investments?
A greenfield offshore investment involves developing a completely new project from scratch, with no existing infrastructure in place. A brownfield offshore investment involves expanding, upgrading, or repurposing an existing facility. The core difference is risk profile: greenfield projects offer higher potential returns but carry greater execution uncertainty, while brownfield projects are lower risk but often have limited upside.
Here is a quick comparison of the two approaches:
- Greenfield: Higher capital requirement, longer development timeline, greater permitting complexity, but full control over design and technology choices
- Brownfield: Lower upfront cost, faster time to production, existing workforce and supply chain relationships, but constrained by legacy infrastructure decisions
Many investors prefer brownfield opportunities in the current environment because they reduce the time between capital commitment and revenue generation. However, greenfield projects dominate in offshore wind, where there is simply no existing infrastructure to build on in most new markets.
Why do investors prioritize workforce readiness in offshore project assessment?
Investors prioritize workforce readiness because a delayed project start directly erodes returns, and offshore projects are particularly vulnerable to delays caused by crew and personnel shortages. In safety-critical environments, you cannot substitute an unqualified worker for a qualified one without increasing operational and liability risk.
During project due diligence, sophisticated investors now assess whether a developer has secured access to the right technical personnel, not just the right equipment and permits. This includes certified offshore workers, specialized engineers, and experienced project managers who understand the regulatory requirements of the operating region.
Workforce availability has become a genuine constraint in several active offshore markets. The expansion of offshore wind in particular has created competition for skilled marine and electrical personnel that was not present a decade ago. Projects that can demonstrate a clear staffing pipeline for offshore roles are better positioned to close financing and meet construction milestones.
Where are the most active offshore investment regions right now?
In 2026, the most active offshore investment regions are the North Sea, the Asia-Pacific corridor from Taiwan to Australia, the US Gulf of Mexico, and the Middle East. Each region is active for different reasons, driven by a mix of energy policy, resource availability, and infrastructure maturity.
The North Sea remains the most mature offshore wind market globally, with the UK, Netherlands, Denmark, and Germany all advancing large-scale projects. Oil and gas decommissioning is also creating significant activity in parallel.
The Asia-Pacific region is seeing rapid growth in offshore wind, particularly in Taiwan, South Korea, Japan, and Australia, driven by government decarbonization targets and strong industrial demand for clean power.
The US Gulf of Mexico continues to attract deepwater oil and gas investment, while the US East Coast is building out one of the world’s largest offshore wind pipelines.
The Middle East, particularly Saudi Arabia and the UAE, is investing in offshore oil production capacity while simultaneously developing renewable energy projects tied to hydrogen export ambitions.
How iPS Powerful People helps with offshore project staffing
We work directly with project developers, operators, and contractors across all of the regions and sectors covered in this article. With more than 35 years of experience in international offshore staffing, we understand what it takes to get the right people on board before a project start date becomes a problem.
- Full project crewing: We can staff an entire offshore project from survey through installation, not just fill individual roles
- Qualified candidates: Every placement meets QHSE requirements and relevant international safety standards
- Cross-border payroll: We place candidates on our own payroll with full compliance, including A1 certificates within the EU, so you carry no administrative or legal risk
- Local market knowledge: Our offices in the Baltics, Croatia, Saudi Arabia, Mexico, Dubai, and the US give us direct access to regional talent pools and local regulatory expertise
- B Corp certified: We operate to high social and environmental standards, which increasingly matters to investors and project owners with ESG commitments
Whether you need a single specialist or a complete project crew, we are ready to help you move fast without cutting corners. Learn more about who we are or get in touch with our team to discuss your staffing needs.