
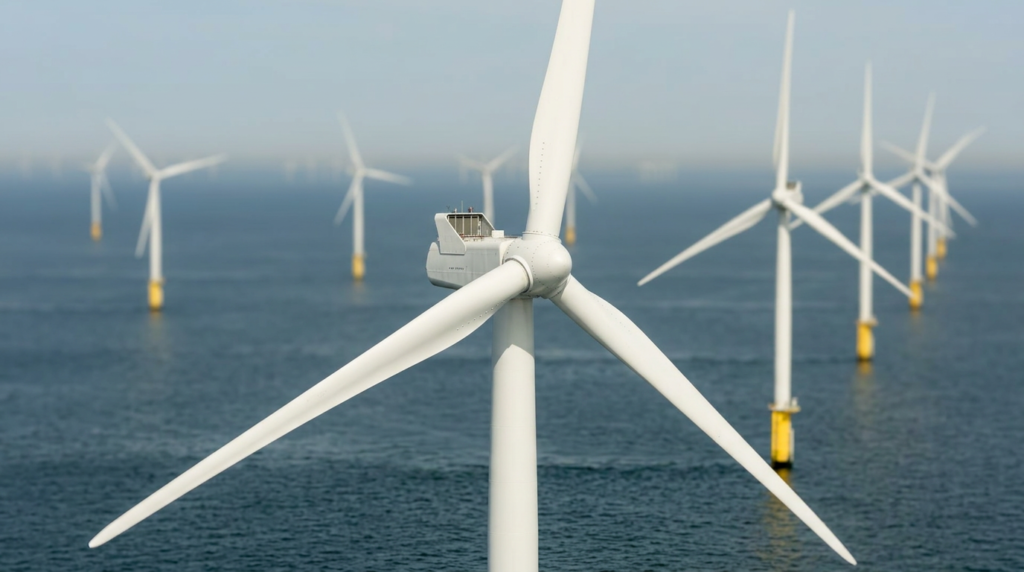
The countries that invest most in offshore wind are China, the United Kingdom, Germany, the Netherlands, and Denmark — with China leading by a significant margin. Together, these five nations account for the vast majority of global offshore wind capacity and capital spending. The sections below break down what drives investment in each region, which emerging markets are catching up, and what all of this means for the people who build and operate these projects.
Which countries lead global offshore wind investment?
China is by far the largest investor in offshore wind, followed by the United Kingdom, Germany, the Netherlands, and Denmark. These five countries have built the most installed capacity, attract the most private capital, and set the pace for global offshore wind development. The US is growing fast and is expected to close the gap significantly through 2026 and beyond.
Here is a quick overview of the leading offshore wind nations and what makes each one stand out:
- China: Dominates in volume. Massive state-backed projects, low turbine costs, and aggressive national targets have made China the world’s largest offshore wind market by installed capacity.
- United Kingdom: Europe’s offshore wind pioneer. The UK has deep water expertise, a mature supply chain, and a long track record of large-scale projects in the North Sea.
- Germany: Strong industrial base and ambitious expansion targets, particularly in the Baltic and North Sea zones.
- Netherlands: A compact but highly active market with several major projects underway and a well-developed port and logistics infrastructure.
- Denmark: The birthplace of offshore wind. Danish companies and institutions continue to shape global standards and technology.
If you are looking for offshore wind job opportunities, these are the markets where activity is highest and where demand for skilled professionals is strongest.
What is driving offshore wind investment in Europe?
Offshore wind investment in Europe is driven by three main forces: energy security, climate targets, and falling technology costs. After the energy price volatility of recent years, European governments have accelerated their offshore wind programmes to reduce dependence on imported fossil fuels. EU policy frameworks and national auction systems have created stable revenue mechanisms that make long-term investment attractive to private capital.
The North Sea has become the centre of gravity for European offshore wind, with the UK, Germany, the Netherlands, Denmark, and Belgium all competing for seabed rights and supply chain capacity. Floating offshore wind — which opens up deeper water sites — is moving from the pilot phase to early commercial scale, particularly off the coasts of Norway, Scotland, and Portugal.
Governments are also investing heavily in grid infrastructure, port upgrades, and workforce development, recognising that turbines in the water are only part of the equation. The broader energy and maritime industries are being reshaped by this investment cycle.
How does China’s offshore wind spending compare to the rest of the world?
China’s offshore wind spending dwarfs every other country. In recent years, China has installed more offshore wind capacity annually than the rest of the world combined. This is the result of large state-owned energy companies, government-set capacity targets, a domestic turbine manufacturing industry that has driven costs down sharply, and streamlined permitting processes that allow projects to move from approval to operation quickly.
Where European projects often take six to ten years from planning to first power, Chinese projects can move considerably faster. The trade-off is that Chinese offshore wind is largely a domestic story — the technology, labour, and supply chain are predominantly local, which limits the international staffing and contracting market compared to European projects.
For international contractors and crew, Europe and, increasingly, the US and Asia-Pacific represent the most accessible markets. China’s scale is impressive, but its offshore wind sector operates largely within its own ecosystem.
Which emerging markets are entering the offshore wind sector?
Several markets are making their first serious moves into offshore wind in 2026. Taiwan, South Korea, Japan, Vietnam, and Poland are among the most active, each with pipeline projects that are attracting international developers, contractors, and crew.
- Taiwan: Has already commissioned its first large-scale projects and is building out a local supply chain with strong support from European developers.
- South Korea: Ambitious national targets and a large domestic shipbuilding industry give it a strong foundation for rapid growth.
- Japan: Moving carefully but steadily, with floating wind particularly relevant given its deep coastal waters.
- Vietnam and Southeast Asia: Early-stage but high-potential, driven by strong wind resources and energy demand growth.
- Poland and the Baltic region: The Baltic Sea is becoming a major new frontier for European offshore wind, with Poland, Estonia, Latvia, and Lithuania all advancing projects.
Emerging markets typically rely heavily on international expertise in the early stages of their offshore wind programmes, which creates real opportunities for experienced professionals and staffing partners with regional knowledge.
What factors determine how much a country invests in offshore wind?
A country’s offshore wind investment level is shaped by a combination of natural resources, policy frameworks, grid capacity, and industrial capability. No single factor determines investment on its own — it is the interaction between them that creates the conditions for a functioning market.
The most important factors are:
- Wind resource: Consistent, high-speed offshore winds make projects more productive and financially viable.
- Government policy: Auction systems, power purchase agreements, and capacity targets give developers the revenue certainty they need to commit capital.
- Grid infrastructure: Offshore wind needs onshore grid capacity to absorb the power it generates. Countries that invest in grid upgrades can absorb more offshore capacity.
- Seabed conditions and water depth: Shallow coastal waters are cheaper to develop with fixed-foundation turbines. Deeper water requires floating technology, which is more expensive.
- Supply chain maturity: Countries with established ports, vessel fleets, and component manufacturers can develop projects faster and at lower cost.
- Financing conditions: Access to low-cost capital and clear regulatory frameworks attracts institutional investors and reduces project risk.
How does offshore wind investment affect demand for skilled workers?
Higher offshore wind investment directly increases demand for skilled workers across a wide range of disciplines. Installation, operations and maintenance, cable laying, surveying, commissioning, and project management all require experienced professionals — and the global talent pool has not kept pace with the growth in projects.
The skills gap is most acute in roles that combine offshore experience with technical specialisation: electrical engineers, dynamic positioning officers, marine warranty surveyors, QHSE managers, and turbine technicians. As new markets like Poland, Taiwan, and South Korea ramp up, they compete for the same relatively limited pool of internationally experienced professionals.
This is not a short-term issue. Industry projections consistently show that workforce demand in offshore wind will grow substantially through the end of the decade, making experienced crew and technical staff one of the sector’s most important resources.
How iPS Powerful People helps with offshore wind staffing
We have been placing professionals in the energy and maritime sectors for more than 35 years, and offshore wind is one of our most active areas of work. Whether you need a single specialist or a full project crew, we handle the sourcing, screening, contracting, and payroll — so you can focus on delivering the project.
- Crewing and project staffing: We staff offshore wind vessels and installations from survey through to commissioning, covering every role from blue collar to senior management.
- International reach with local knowledge: We have offices and representatives in the Baltics, the Netherlands, the UK, Dubai, Mexico, and beyond — which means we know the local labour markets, regulations, and candidate pools in the regions where offshore wind is growing fastest.
- Cross-border payroll and compliance: We take candidates onto our own payroll, manage A1 certificates within the EU, and handle full compliance with local employment law. You carry no administrative risk.
- Full project outsourcing: If you need us to manage the entire workforce for a project, we can do that too — from resource planning through to final demobilisation.
- B Corp certified: We meet high standards for social and environmental performance, which aligns with the sustainability commitments that matter to the offshore wind sector.
Offshore wind investment is accelerating, and so is the competition for the right people. Learn more about who we are or get in touch with our team to discuss how we can support your next project.