
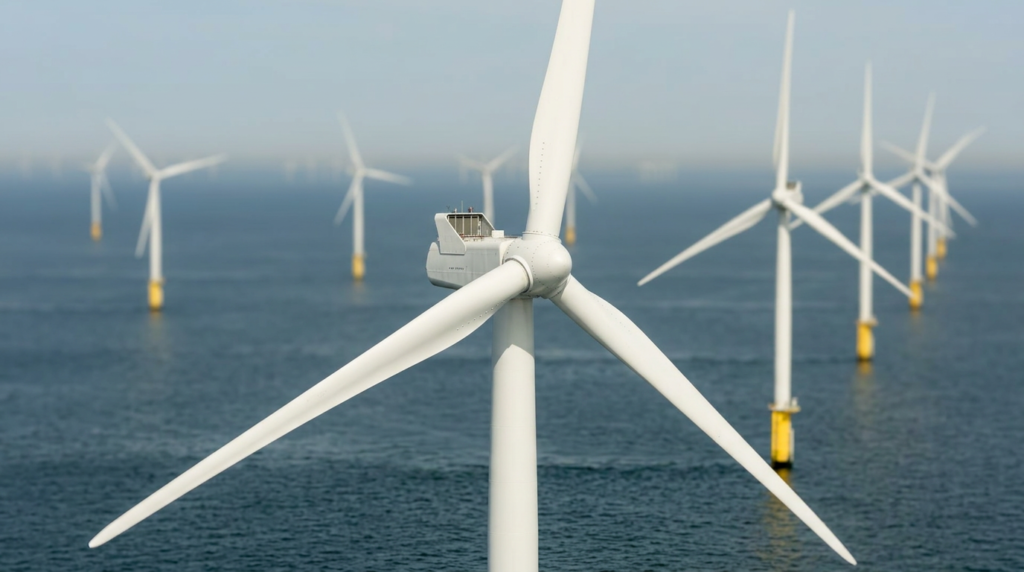
The offshore wind markets with the strongest ROI right now are the UK, the Netherlands, Taiwan, and the US East Coast — each offering a combination of mature policy frameworks, grid infrastructure, and high energy demand. Returns vary significantly depending on water depth, government support mechanisms, and local supply chain maturity. Below, we break down the key factors that drive profitability and help you identify where to focus your investment.
What factors determine ROI in offshore wind markets?
ROI in offshore wind is shaped by four main variables: energy yield, capital expenditure, revenue certainty, and operational costs. A market can look attractive on paper but deliver poor returns if grid connection costs are high, permitting timelines are unpredictable, or the qualified workforce supply is thin. The interaction between these factors determines whether a project actually delivers on its financial projections.
Energy yield depends on wind resource quality and turbine capacity. Capital expenditure is driven by water depth, distance from shore, and local construction costs. Revenue certainty comes from government contracts or power purchase agreements. Operational costs include maintenance, crew logistics, and compliance with local labor regulations.
- Wind resource: Higher average wind speeds directly increase annual energy output
- Water depth: Shallower water means lower foundation costs for fixed-bottom projects
- Grid access: Markets with strong onshore grid infrastructure reduce connection costs
- Policy stability: Long-term contracts reduce revenue risk and attract lower-cost financing
- Supply chain maturity: Established local suppliers keep procurement costs competitive
Which offshore wind regions are attracting the most investment right now?
In 2026, the regions attracting the most offshore wind investment are Northwest Europe, the Asia-Pacific (particularly Taiwan and South Korea), and the US East Coast. These markets combine strong wind resources with active government auction programs and growing domestic supply chains, making them the most bankable locations for new development.
Northwest Europe remains the global benchmark. The UK, the Netherlands, Germany, and Denmark have decades of operational experience, established installation infrastructure, and clear regulatory pathways. The North Sea is entering a new phase of large-scale buildout, with multi-gigawatt projects now standard.
Taiwan has emerged as Asia’s most active offshore wind market, driven by aggressive government targets and feed-in tariff mechanisms. South Korea is scaling up rapidly with ambitious capacity targets. In North America, the US East Coast continues to attract major developer commitments despite ongoing permitting complexity, particularly in states like New York, New Jersey, and Massachusetts.
For developers exploring energy and maritime industries across these regions, understanding the local regulatory and workforce landscape is as important as the financial model.
How do government policies affect offshore wind returns by market?
Government policy is the single biggest lever on offshore wind ROI. Markets with long-term contracts for difference (CfDs), stable permitting processes, and local content requirements deliver more predictable returns than those relying on merchant pricing or subject to frequent regulatory changes.
In the UK, the CfD mechanism provides developers with a fixed strike price over 15 years, significantly de-risking revenue. The Netherlands uses a similar tender system with SDE++ subsidies. These structures allow developers to secure project financing at competitive rates, which has a direct and measurable impact on project economics.
In contrast, markets still developing their regulatory frameworks — including several Southeast Asian and Middle Eastern markets — carry higher policy risk. This doesn’t make them unattractive, but it does mean developers need to price that uncertainty into their return expectations. The US market sits somewhere in between: federal support through the Inflation Reduction Act has been positive, but state-level permitting and interconnection processes remain variable.
What’s the difference between fixed-bottom and floating wind ROI?
Fixed-bottom offshore wind generally delivers higher and more predictable ROI today, while floating wind carries greater upside potential but higher near-term risk. The difference comes down to technology maturity, installation costs, and the scale of available resource.
Fixed-bottom technology is proven at commercial scale. Monopile and jacket foundations work well in water depths up to roughly 60 meters, covering most of the best near-shore sites in Europe and Asia. Levelized cost of energy (LCOE) has fallen sharply over the past decade, and project financing is well understood by lenders.
Floating wind opens access to deeper water sites — including the best resources off the coasts of Norway, Scotland, Japan, and the US West Coast — but costs remain significantly higher. Most floating projects currently require some form of government support to be financially viable. As the technology scales and supply chains mature, the ROI gap between fixed-bottom and floating is expected to narrow through the late 2020s and into the 2030s.
How does workforce availability impact offshore wind project returns?
Workforce availability has a direct and often underestimated impact on offshore wind project returns. Delays caused by crew shortages, skills gaps, or compliance failures on international hires can push project timelines and budgets significantly off course — particularly during the installation and commissioning phases when day rates for vessels and equipment are running continuously.
The offshore wind sector requires a highly specific mix of skills: marine coordinators, offshore installation engineers, turbine technicians, cable specialists, and safety-critical crew. In fast-growing markets like Taiwan or the US East Coast, local talent pools are still developing, which means developers increasingly rely on internationally mobile professionals.
Managing international workforce compliance — including work permits, A1 certificates, local labor law, and payroll structures across multiple jurisdictions — adds complexity that can erode returns if handled poorly. Markets with strong local workforce pipelines, like the UK and the Netherlands, carry lower execution risk on this dimension. Developers entering newer markets should factor recruitment lead times and compliance costs into their project planning from day one. Reviewing available offshore wind roles gives a useful indication of current talent availability across key markets.
Which offshore wind market should developers prioritise in 2026?
For developers seeking the best balance of risk and return in 2026, the UK and the Netherlands remain the top priorities, followed closely by Taiwan for Asia-Pacific exposure. These markets combine proven policy frameworks, established supply chains, and strong wind resources with manageable execution risk.
Developers with higher risk appetite and longer investment horizons should also watch the US East Coast closely. Despite permitting complexity, the sheer scale of the market and the federal incentive environment make it one of the most significant long-term opportunities globally.
Emerging markets in the Middle East and Southeast Asia are worth monitoring but require careful due diligence on regulatory stability and local workforce capacity. The right market ultimately depends on your project development timeline, financing structure, and operational capabilities — but in 2026, Northwest Europe still sets the benchmark for bankable offshore wind returns.
How iPS Powerful People helps with offshore wind workforce solutions
Getting the right people in place is what turns a well-structured offshore wind project into a project that actually delivers on time and on budget. We have been placing specialists in the renewables and maritime sectors for over 35 years, and we understand the workforce challenges that come with operating across multiple markets simultaneously.
- Full project crewing: We can manage the complete workforce for an offshore wind project, from survey through to installation and commissioning, not just individual placements
- International payroll and compliance: We take candidates onto our own payroll, handling A1 certificates, local labor law compliance, and contract management across jurisdictions so you carry no administrative or legal risk
- Local market knowledge: With offices in the Netherlands, the Baltics, Croatia, Dubai, Saudi Arabia, Mexico, and the US, we know the local talent pools and regulatory requirements in the markets where you are building
- QHSE screening: Every candidate we place is screened against international safety standards and QHSE requirements, which is a non-negotiable condition for any placement we make
- B Corp certified: Our B Corp certification reflects our commitment to responsible business practices, which aligns with the sustainability standards increasingly expected by offshore wind developers and their stakeholders
Whether you need a single specialist or a complete project crew, we are ready to help you staff your offshore wind project efficiently and compliantly. Learn more about us or get in touch with our team to discuss your workforce needs.